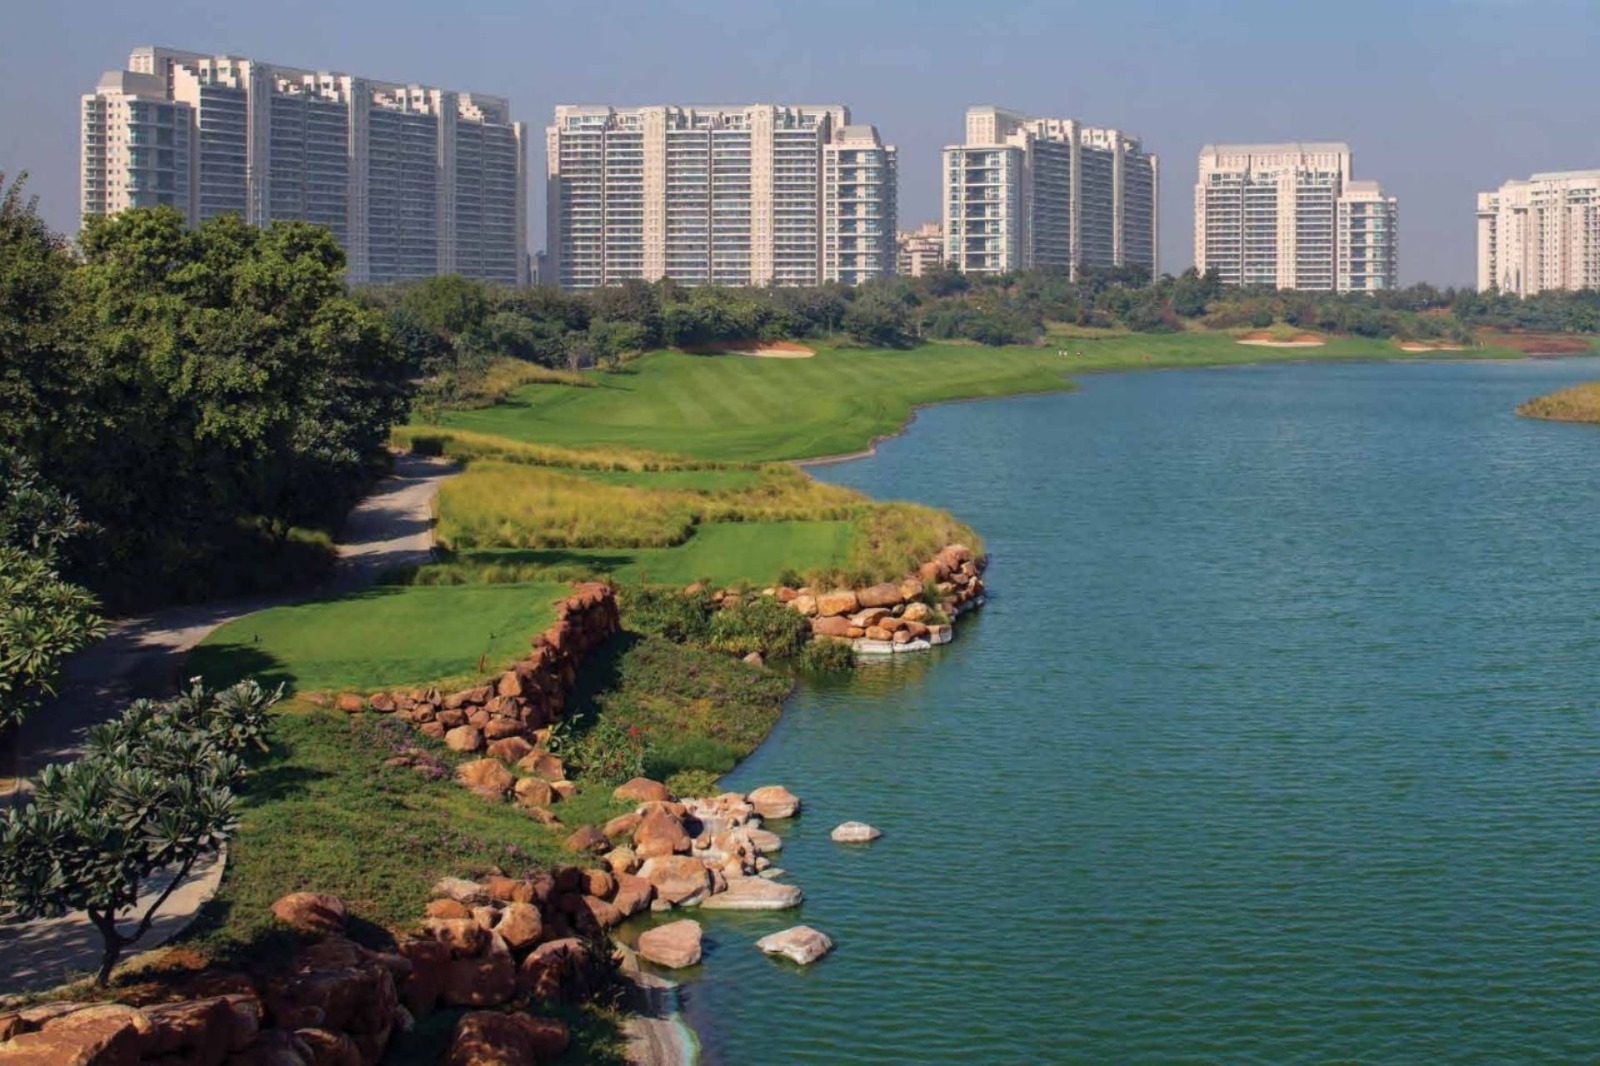
A Gurgaon real estate is stirring a lively debate on how investors judge returns across asset classes. Wealth manager Peeyush Aggarwal shared a case of an investor who bought a DLF Camellia, Gurgaon apartment in 2014 for ₹24 crore. Eleven years later, the flat is valued at ₹64 crore. Even after this headline gain, the investor’s XIRR, after paying ₹3 crore in interest and maintenance over the holding period, comes in below 9%, Aggarwal noted.
The same investor, Aggarwal added, separately considers a 14% IRR on a compounding financial asset “suboptimal.” The contrast, he argues, points to expectation bias, where the psychological comfort of a large, tangible, illiquid asset can skew how returns are perceived versus smaller, liquid, and steadily compounding investments.
Gurgaon Real Estate: What the numbers actually say?
- Purchase (2014): ₹24 crore
- Indicative value (after 11 years): ₹64 crore
- Carrying costs reported: ₹3 crore (interest + maintenance)
- Stated result: XIRR below 9% (per Aggarwal)
For context, the headline CAGR from ₹24 crore to ₹64 crore over 11 years is roughly ~9.3% before accounting for costs and cash-flow timing. With ₹3 crore of outflows across the period and the irregular timing that XIRR captures, the sub-9% figure aligns with the picture Aggarwal described.
(Note: The post did not detail taxes, stamp duty, or rental inflows/outflows, which would also affect net returns.)
Why perception diverges
Illiquidity vs. liquidity: A premium address and a marquee asset can feel “safer” and more prestigious than a dematerialized portfolio, even when the time-weighted, cost-adjusted return is lower. By contrast, compounding financial assets (equity funds, for example) are liquid, mark-to-market daily, and emotionally harder to hold through volatility, even if their IRR can be meaningfully higher over long horizons.
Capital tie-up: Large real-estate allocations lock in concentration risk and opportunity cost. The cash that could have compounded elsewhere is effectively anchored in one illiquid position, with periodic cash drains (interest, upkeep).
Framing effect: A multi-crore jump in nominal value sounds impressive; a single-digit XIRR often doesn’t. But XIRR is the tool that reconciles “money in, money out, and when,” which is what matters for true performance.
Timing and Intangibles
Aggarwal’s post drew two notable responses that sharpen the debate:
- Timing and rentals matter (Puneer Suri): Real estate, he argued, is highly entry-timing dependent. On a long-term basis, he suggested ~12% including rental is achievable in realty; in this specific case, he added, buying “four years back” at a similar price point would have produced a very different IRR.
- Intangible spillovers (CA Rahul Srivastava): He cautioned that a strict input-output comparison misses intangible benefits, from social capital to client introductions, that a premium address can catalyze.
Both points are valid lenses: one is market-driven (timing, yield), the other context-driven (network effects). Neither negates the XIRR math; they reframe what counts as “return.”
Takeaways for serious investors
- Measure what you actually earned: Use XIRR, not headline price jumps, and include all cash flows (maintenance, interest, major repairs).
- Compare like for like: Put the risk, liquidity, and concentration of a luxury flat next to a diversified, liquid compounding alternative before calling 14% “suboptimal.”
- Model timing sensitivity: Real estate outcomes can hinge on entry cohort and rental yield; run scenarios to see how much timing explains.
- Account for opportunity cost: A ₹24-crore cheque in one illiquid asset crowds out other compounding engines for a decade.
- Acknowledge intangibles, but separate them: If a property helps win business, record that outside the property IRR to avoid muddying investment performance with operating gains.
This Gurgaon case isn’t a verdict against real estate. It’s a reminder that big, visible gains can mask modest, time-adjusted returns after costs and that liquidity and compounding deserve equal billing in any long-term plan. If investors hold illiquid trophy assets while dismissing double-digit, liquid compounding as “not good enough,” that’s not prudence; it’s a framing problem.
Also Read: Shreya Malpani on Women Leading a Century-Old Family Business