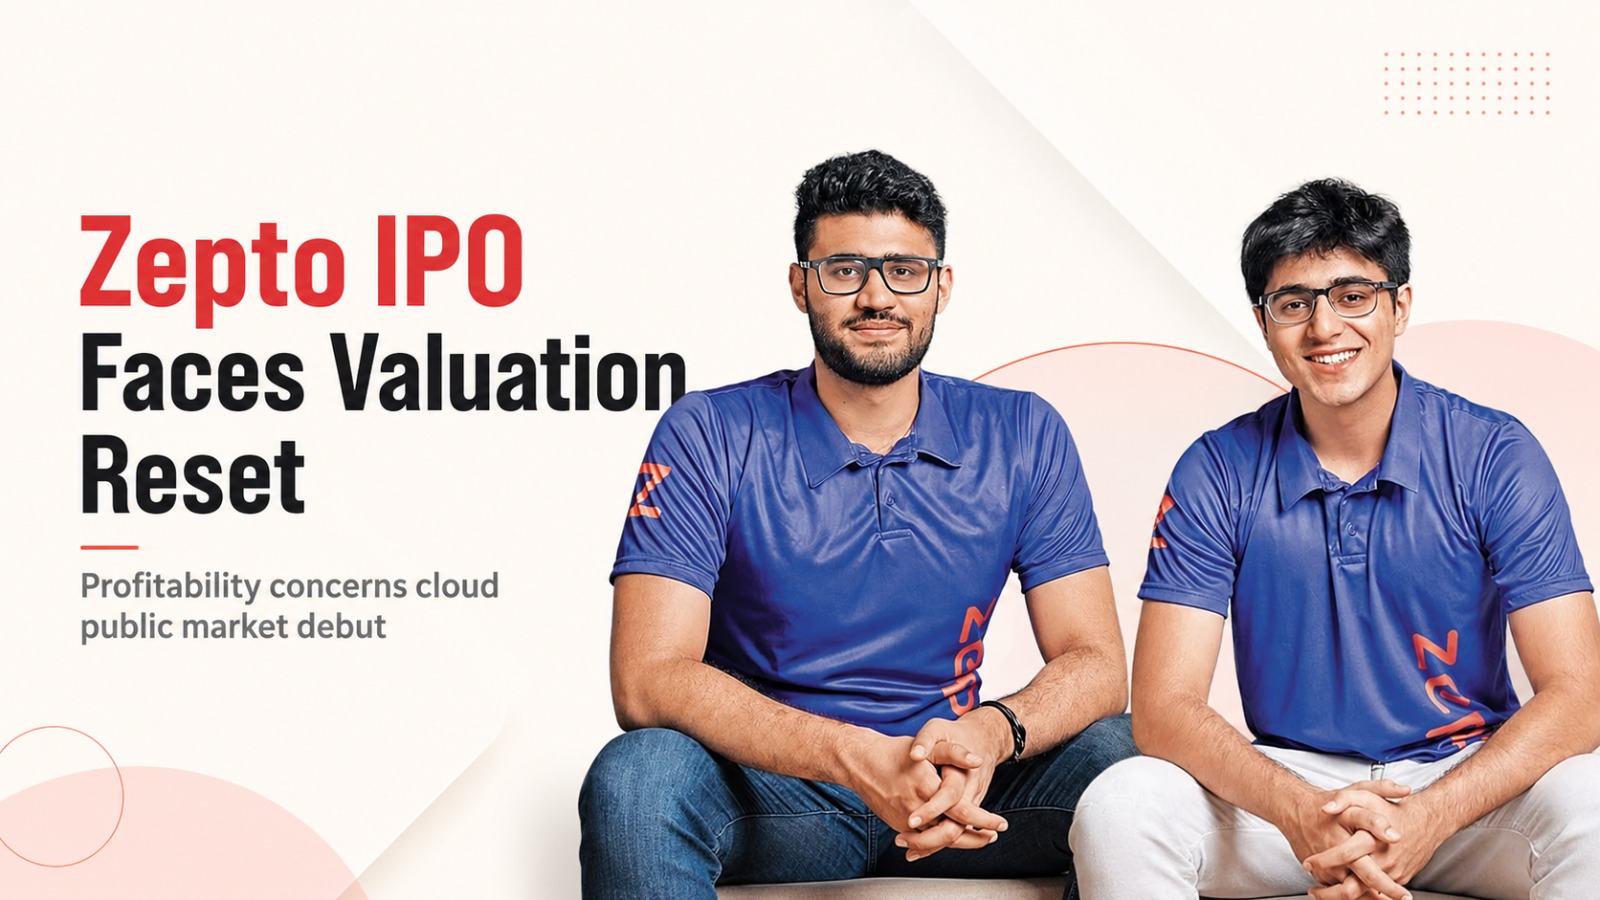
Zepto may have to enter the public market at a considerably lower valuation than the $7 billion it secured in its October 2025 funding round, with prospective investors placing greater weight on profitability and spending discipline.
Overseas funds have shown interest in the quick-delivery company at a pre-money valuation of about $4.5 billion. Domestic institutional investors are understood to be considering an even lower range of $3 billion to $3.5 billion.
The figures remain part of ongoing negotiations and do not represent a final IPO price. The size of the offering, the valuation and the listing schedule could all change before the process is completed.
Zepto is seeking to raise up to $850 million from the public issue. Its draft prospectus outlines a fresh share issue worth ₹80.1 billion, or approximately $831 million, along with an offer for sale involving 113 million shares held by existing investors.
Investor attention shifts from expansion to earnings
The valuation discussions reflect a broader change in investor sentiment towards quick commerce.
Companies in the sector have spent heavily to build delivery networks, open dark stores and acquire customers in major urban markets. That expansion helped quick-commerce platforms attract substantial funding, but investors are now looking for clearer evidence that growth can eventually translate into sustainable earnings.
Zepto’s spending levels and the uncertainty surrounding its profitability timeline have become central to the pricing conversation ahead of the IPO.
This does not mean the company’s final valuation has been determined. It does, however, show that the public-market debate is likely to focus less on rapid expansion alone and more on the financial cost of maintaining that growth.
The different valuation figures circulating around Zepto also need to be read carefully. The price discussed with overseas institutions, estimates from domestic investors and valuations implied by private share transactions come from separate parts of the market. They point to a more cautious environment, but they do not amount to one settled price for the company.
Unlisted shares also reflect weaker sentiment
Zepto shares have been trading in the unlisted market at about ₹39 each, implying a company valuation of roughly ₹492 billion, or $5.1 billion.
The shares were reported to be about 33 per cent below their March level. While prices in the private market do not automatically determine an IPO valuation, the decline adds to signs that investors have become more selective about how they value fast-growing consumer technology businesses.
The caution is also visible in the performance of listed quick-commerce companies. Swiggy’s shares were nearly 29 per cent below their late-2024 debut price at the time of the cited reporting.
Together, these developments suggest that Zepto will be approaching investors at a time when growth stories are being tested against operating costs, competitive pressure and the ability to move towards profitability.
Fresh capital will support dark stores and technology
Zepto plans to use the proceeds from the fresh share issue to expand its dark-store network, strengthen its technology systems and support its wider growth plans.
Dark stores are a core part of the quick-commerce model, allowing companies to position inventory close to customers and process orders quickly. Expanding that network can improve coverage and delivery capacity, but it also requires continued investment.
That balance is likely to be closely examined during the IPO process. Investors will have to assess whether further expansion can improve the company’s economics over time or add to spending before profitability is reached.
Zepto competes with Blinkit, Swiggy and Tata Group-owned BigBasket, as well as Amazon’s India business. Competition across the sector has intensified as companies expand product selections, improve delivery times and build denser fulfilment networks.
Existing investors to participate in the offering
Zepto is backed by Nexus Venture Partners, Glade Brook Capital Partners and StepStone Group.
The IPO is being managed by Axis Capital, Motilal Oswal Investment Advisors and the Indian units of Morgan Stanley, HSBC and Goldman Sachs.
The presence of a fresh issue alongside an offer for sale means the proposed IPO has two separate purposes. New capital will go to Zepto for business expansion and technology investment, while the offer-for-sale portion will allow existing shareholders to sell part of their holdings.
For Zepto, the final valuation will be more than a headline number. It will indicate how public-market investors judge the quick-commerce model after years of rapid growth, aggressive investment and rising scrutiny of profitability.
The company may still secure a sizeable public offering, but the early discussions suggest that investors are no longer pricing expansion without asking what it costs and when it will produce returns.
Also Read: OnePlus India Shutdown Rumours Return, but the Company Says Operations Remain Normal