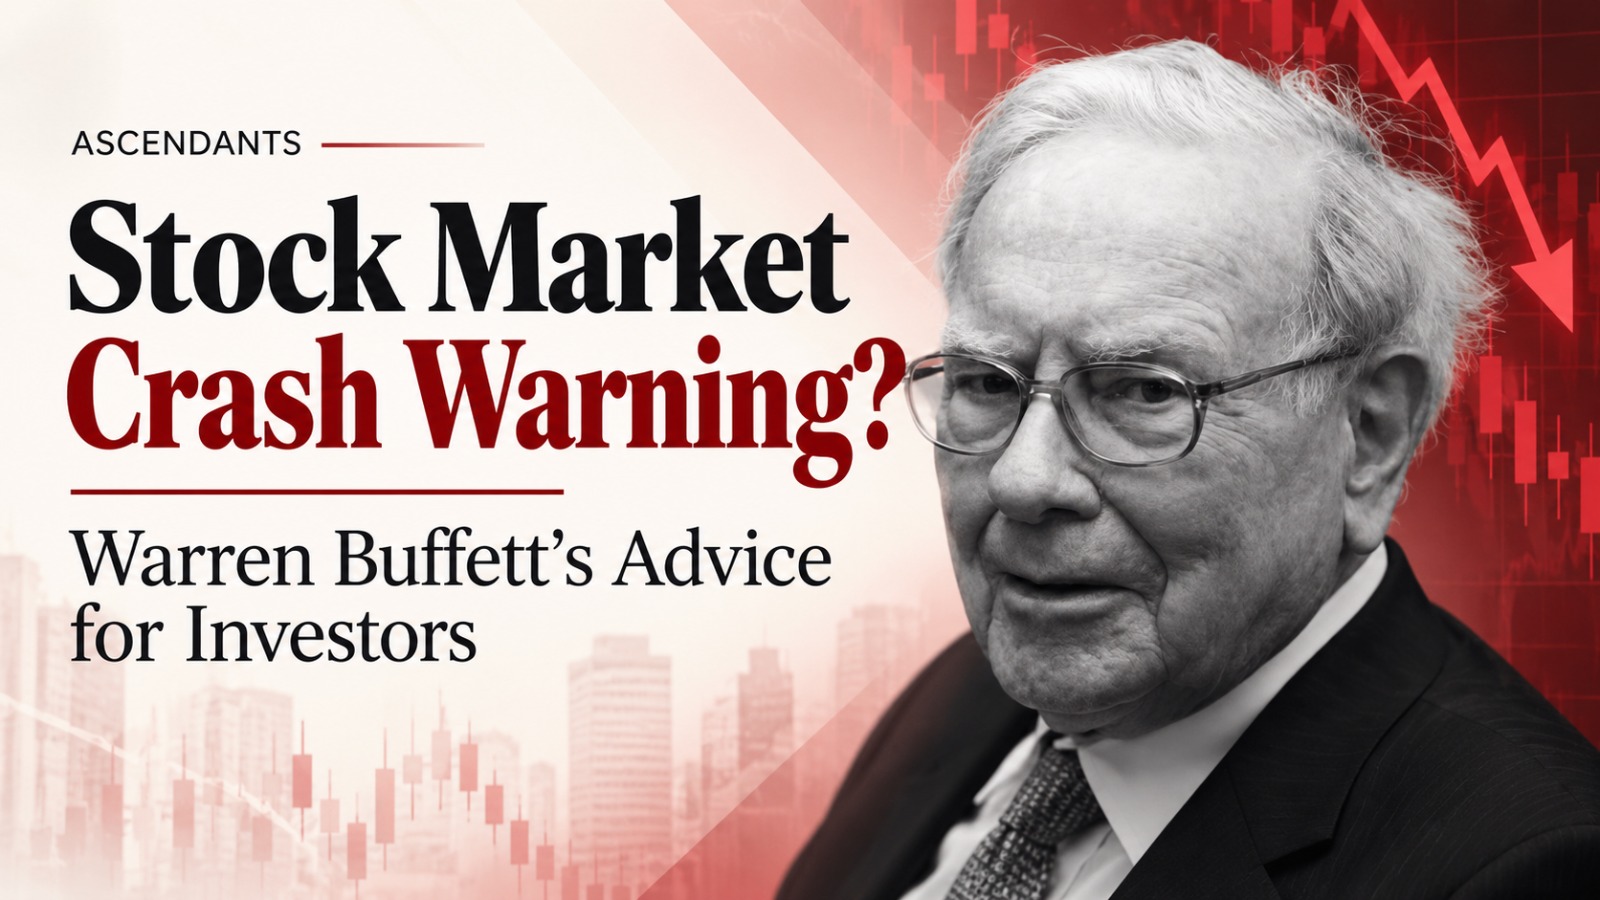
US Stock Market Crash 2026: With the Shiller CAPE ratio above 40, rising bond yields and questions surrounding the AI spending boom, Wall Street is facing an uncomfortable comparison with the 2000 dot-com crash. But Warren Buffett’s investing philosophy offers a different response to market uncertainty.
The US stock market has enjoyed a remarkable rally over the past four years, but some of the indicators that preceded earlier market crashes are flashing warning signs again. With stocks trading at historically expensive valuations and investors questioning whether the artificial intelligence boom can sustain its momentum, concerns about a possible market correction are growing.
The S&P 500 has gained nearly 120% since the bull market began in October 2022, driven largely by enthusiasm surrounding AI. However, the rally has recently lost some momentum.
Reports show the benchmark index falling nearly 2% over the preceding week, while the technology-heavy Nasdaq Composite declined more than 4%.
What makes the situation particularly noteworthy is a valuation indicator that has climbed to levels last associated with the dot-com bubble.
Yet, for legendary investor Warren Buffett, the question has never been whether investors can predict the next crash. His long-standing approach focuses on identifying businesses capable of surviving difficult market conditions and creating wealth over time.
Why are investors worried about a US stock market crash?
One of the most closely watched warning signals is the Shiller cyclically adjusted price-to-earnings ratio, commonly known as the CAPE ratio.
The indicator compares the S&P 500’s market price with the average inflation-adjusted earnings of its constituent companies over the previous 10 years. By accounting for a longer period, it helps investors assess valuations without relying entirely on a single year’s earnings.
In October 2026, the ratio moved above 40, more than twice its reported long-term average of approximately 17.4.
That is an unusual level.
The CAPE ratio previously reached a record 44.2 in December 1999, shortly before the dot-com bubble burst. The subsequent downturn wiped out substantial stock market wealth and triggered a prolonged bear market.
Another historical comparison comes from 1929, when the CAPE ratio reached approximately 32.6 before the Great Depression-era market collapse.
Buffett’s favourite valuation indicator is also raising concerns
The Shiller CAPE ratio is not the only measure suggesting that American stocks have become expensive.
Another widely followed indicator compares the total value of the US stock market with the country’s gross domestic product. Often called the Buffett Indicator, it provides a broad measure of stock market valuations relative to the size of the economy.
The ratio was reported at approximately 244% in October 2026, indicating that the stock market’s value was more than twice the country’s annual economic output.
For perspective, Buffett previously warned about valuations approaching 200%, describing such levels as “playing with fire.”
Is the AI boom beginning to resemble the dot-com bubble?
Artificial intelligence has been a major force behind the stock market’s rise, particularly as investors have poured money into companies developing chips, software and cloud infrastructure.
Some of the gains have been extraordinary.
Nvidia reportedly gained around 900% over five years, while Micron Technology rose approximately 200% during 2026, according to figures cited in an October 15 market analysis.
But the enormous investments required to support AI development have also raised questions about future profitability.
Amazon, Microsoft, Alphabet and Meta Platforms were projected to spend more than $700 billion collectively during 2026, reflecting the scale of investment in AI-related infrastructure.
Rising bond yields add another complication by increasing borrowing costs. This could put pressure on companies financing expensive data centres and other infrastructure projects.
If major technology companies reduce their AI spending, businesses supplying chips, memory, computing infrastructure and related services could also feel the impact.
The concern is not necessarily that AI will fail as a technology. It is whether the financial returns generated by AI businesses will eventually justify the expectations already reflected in their share prices.
What Warren Buffett warned investors about before the dot-com crash
In a 1999 essay published by Fortune, Buffett cautioned investors against confusing an industry’s potential to transform society with the financial prospects of individual companies operating within it.
He illustrated the point using the airline industry.
Air travel had transformed transportation, but Buffett noted that 129 airlines had filed for bankruptcy over the preceding 20 years.
His argument was straightforward: an industry can achieve extraordinary technological progress without delivering attractive returns to every investor.
“The key to investing is not assessing how much an industry is going to affect society, or how much it will grow,” Buffett wrote, “but rather determining the competitive advantage of any given company and, above all, the durability of that advantage.”
The lesson became especially relevant when the internet bubble burst in 2000.
The Nasdaq Composite lost approximately 77.55% between March 2000 and October 2002, according to historical performance data presented by YCharts.
Numerous technology companies collapsed, even as the internet continued transforming the global economy.
At the same time, businesses such as Apple, Amazon and Microsoft eventually emerged as industry leaders.
What should investors do if the stock market crashes?
Buffett’s approach suggests that investors should pay greater attention to business quality, valuations and patience than to predictions about the next market downturn.
Companies with durable competitive advantages, sustainable finances and strong underlying businesses may be better positioned to withstand challenging market conditions.
Buffett has frequently described these advantages as economic moats, referring to characteristics that help a business protect its competitive position over time.
He has also emphasised the importance of avoiding emotionally driven investment decisions.
In an October 2008 opinion piece for The New York Times, published during the global financial crisis, Buffett offered one of his most widely quoted principles:
“Be fearful when others are greedy, and be greedy when others are fearful.”
Similarly, excessive optimism can push stock prices far beyond what their underlying earnings prospects justify.
Selling an entire portfolio in anticipation of a crash also presents a problem. Investors would need to correctly predict both when to exit the market and when to return, something that is extremely difficult to accomplish consistently.
How much wealth has Buffett’s long-term strategy created?
Buffett’s investment record illustrates why patience remains central to his philosophy.
Between 1965 and 2025, Berkshire Hathaway shares generated a compounded annual gain of approximately 19.7%, compared with an annualised total return of 10.5% for the S&P 500.
The difference may appear modest when viewed over a single year, but compounding over several decades produces vastly different outcomes.
Berkshire Hathaway’s reported cash balance of approximately $359 billion as of June 30, 2026, also attracted attention amid concerns about stock valuations.
Although a large cash position can provide financial flexibility, it should not automatically be interpreted as a prediction that a stock market crash is imminent.
Will the US stock market crash in 2026?
The warning signs are difficult to dismiss. Equity valuations are elevated, AI-related spending faces increasing scrutiny, and higher borrowing costs are creating pressure across parts of the market.
There are also signs that the rally has become increasingly concentrated.
An October 16 analysis reported that more than a quarter of S&P 500 stocks were trading at least 40% below their all-time highs, while nearly 60% were below their 200-day moving averages.
Still, none of these indicators confirms that a stock market crash will happen in 2026. Expensive markets can remain expensive, and historical comparisons cannot establish the timing or severity of future declines.
For investors, Buffett’s philosophy offers a more useful question than whether the market will fall tomorrow: which businesses are worth owning even if the market becomes significantly more volatile?
The answer rests on competitive strength, financial resilience, reasonable valuations and the ability to remain invested through difficult periods.
Also Read: Why Warren Buffett Wants 90% of His Wife’s Inheritance in Just One Investment?