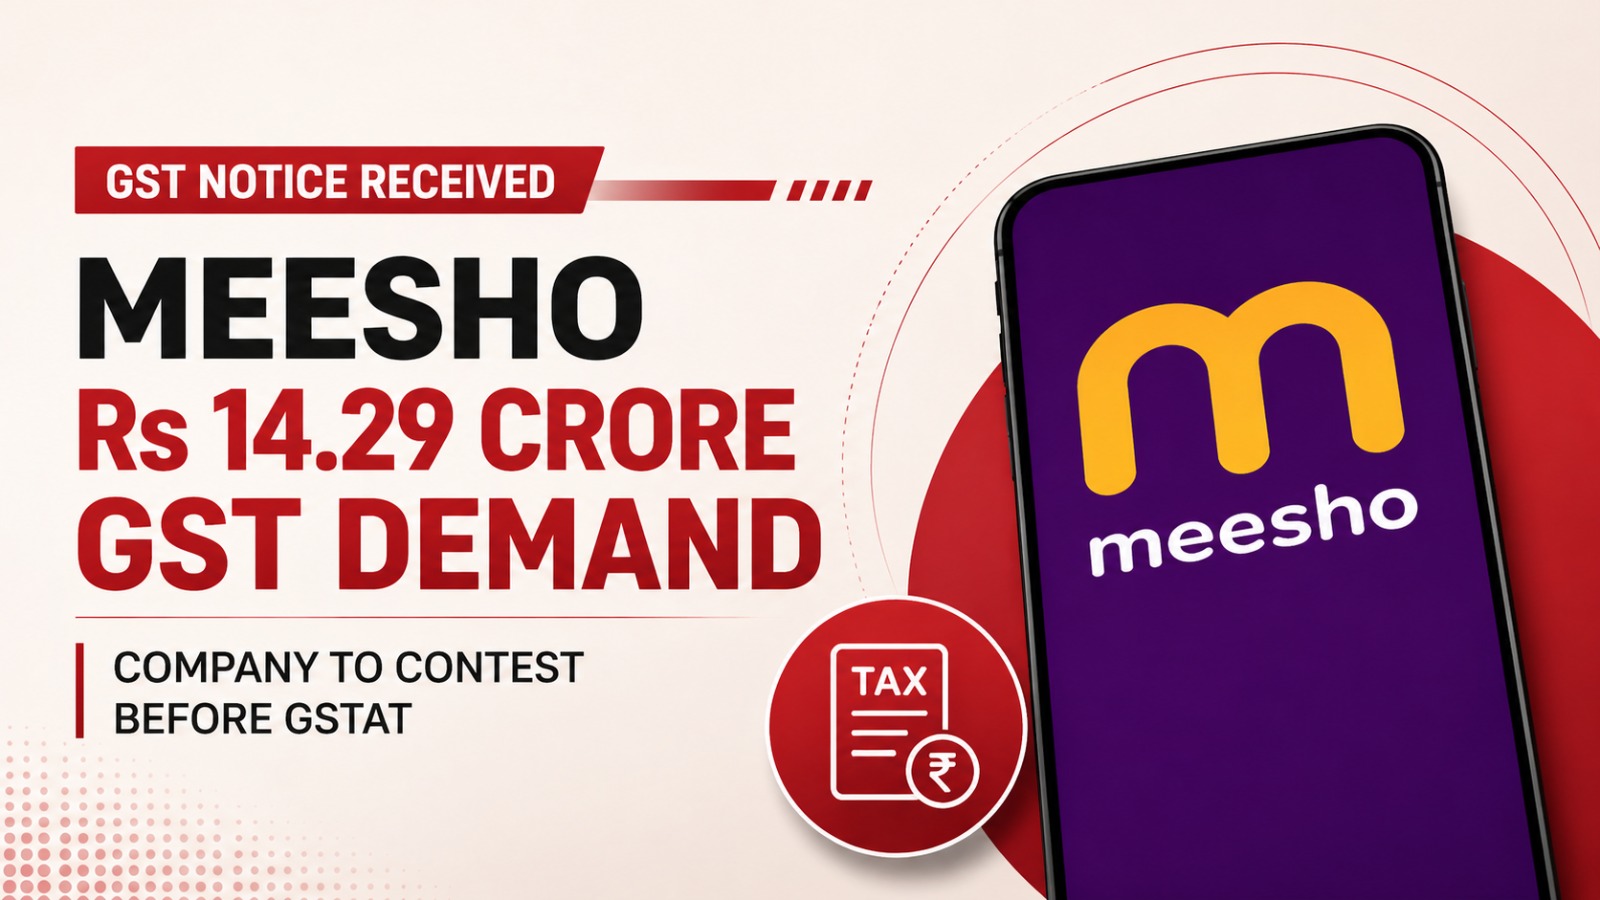
Ecommerce marketplace Meesho has received a GST demand of Rs 14.29 crore and said it will challenge the order before the Goods and Services Tax Appellate Tribunal.
The case relates to tax collected at source under Section 52 of the CGST Act on certain seller transactions between October 2018 and March 2020. The order was passed by the Commissioner Appeals, CGST Thane Commissionerate.
Tax authorities have alleged that Meesho failed to collect TCS on supplies made by individual sellers who sourced products from its platform and later sold them to customers outside the marketplace through social media and other channels.
The appellate authority has upheld the tax demand of about Rs 14.29 crore, along with applicable interest and penalty. However, it has set aside a separate penalty imposed under Section 122.
Meesho has rejected the demand and said it believes the order is “unsustainable and without merit.” The company said it has assessed the matter in detail, taken independent professional advice, and is confident of a favourable outcome.
The company also said the order will not have any material adverse impact on its financial position, operations or business.
The GST matter had earlier been disclosed in Meesho’s prospectus filed in December 2025. The dispute stems from a tax notice received by the company in March.
This is the second tax-related development involving Meesho in recent weeks. The company had earlier disclosed a separate Rs 1,500 crore income-tax demand for assessment year 2023-24, which it also plans to contest.
It is quite interesting that at a particularly delicate period in Meesho’s history, the GST controversy has arisen, especially in view of increased regulatory focus on major digital marketplaces. It is important to note that this situation also poses a broader issue regarding e-commerce platforms regarding the taxation of sellers who source from marketplaces yet conduct transactions elsewhere.
The final outcome will depend on how the appellate tribunal views Meesho’s role in such transactions and whether TCS obligations can be extended to the disputed seller activity.
Also Read: Vaibhav Suryavanshi’s Rise Is Bigger Than a Net-Worth Number