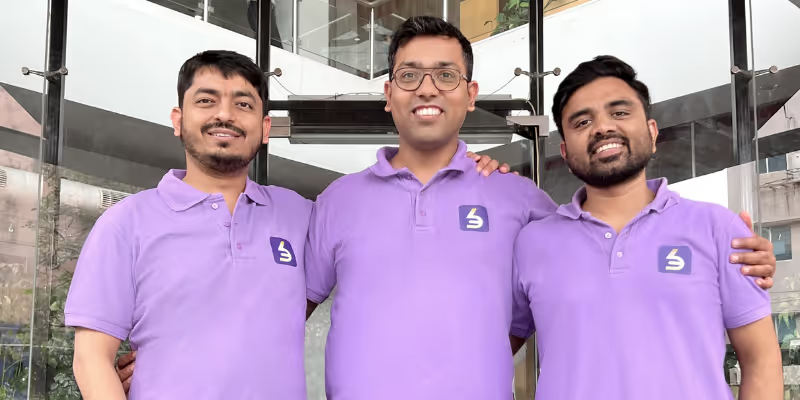
In a funding landscape often driven by rapid scale and high-value users, wealthtech startup Bachatt, founded in 2025 by Anugrah Jain, Ankur Jhavery and Mayank Agarwal is taking a more grounded approach, starting small, building trust, and growing alongside India’s self-employed economy.
The company has raised $12 million in a Series A round led by Accel, with participation from Lightspeed, Info Edge Ventures and existing investors. The fresh capital comes at a time when Bachatt is doubling down on a segment that is large, under-served, and structurally different from the salaried urban market: India’s merchants and self-employed workforce.
At the heart of Bachatt’s strategy is a simple idea, make saving accessible, even for those without fixed monthly incomes. Its core product allows users to begin investing with as little as Rs 100 through debt mutual funds offered by SBI, ICICI and Axis AMC.
The design reflects a clear understanding of its audience: flexible deposits, the ability to pause contributions, and instant withdrawals are built into the product.
This is not just a product decision, it’s a positioning choice. Bachatt is not competing for the same users as high-end wealth apps. Instead, it is trying to become a financial starting point for kirana store owners, jewellery merchants, dealership operators, and a wide range of small business owners who operate outside the salaried ecosystem.
The early signs of traction are notable. The platform has crossed more than two million mutual fund transactions in February 2026 alone, while its overall user base has grown to over 3 million since its launch in May 2025. That combination, activity plus user growth, appears to have played a role in attracting institutional capital at this stage.
Bachatt is now expanding beyond savings into two adjacent areas: wealth management and credit. Both are being built with an AI-led approach. Its wealth solution is designed to track thousands of mutual fund schemes and market signals to identify relatively stable return opportunities. On the credit side, the company is focusing on working capital—a persistent gap for small businesses, aiming to provide fast, predictable access to funds.
The direction is deliberate. Savings builds habit. Habit builds trust. Trust, in turn, opens the door to deeper financial relationships—whether that is investing more or borrowing responsibly. Bachatt is attempting to build this entire lifecycle, step by step, starting with the smallest possible entry point.
Investors seem aligned with this thesis. The emphasis is not just on product, but on behaviour, aligning financial tools with daily income patterns rather than fixed salary cycles. It’s a subtle shift, but one that could define how fintech evolves in markets like India.
The company’s ambitions reflect the scale of the opportunity. It is aiming to serve tens of millions of users over the next one to two years, while building multiple financial products tailored specifically for the self-employed segment.
That ambition comes with its own challenges. Serving this audience requires more than distribution, it demands trust, reliability, and products that can adapt to unpredictable cash flows. The margin for error is thin, and user expectations are fundamentally different from those of traditional investors.
Still, Bachatt’s approach signals a broader shift in India’s fintech narrative. The next phase of growth may not come from adding more features for existing users, but from bringing entirely new segments into the formal financial system, on terms that actually work for them.
Bachatt is betting that the future of fintech in India will be built not on high-value transactions, but on consistent, everyday savings.
Also: Epik raises $1 million to scale electronics-focused quick commerce model