Jar didn’t become a household name in India by selling “fintech”. It grew by selling a feeling: that saving can be automatic, painless, and almost invisible. Launched in 2021 by Nishchay AG and Misbah Ashraf, the Bengaluru-based startup built its identity around tiny, frequent deposits, often routed into digital gold via UPI, aimed at first-time savers who don’t begin with SIPs or spreadsheets.
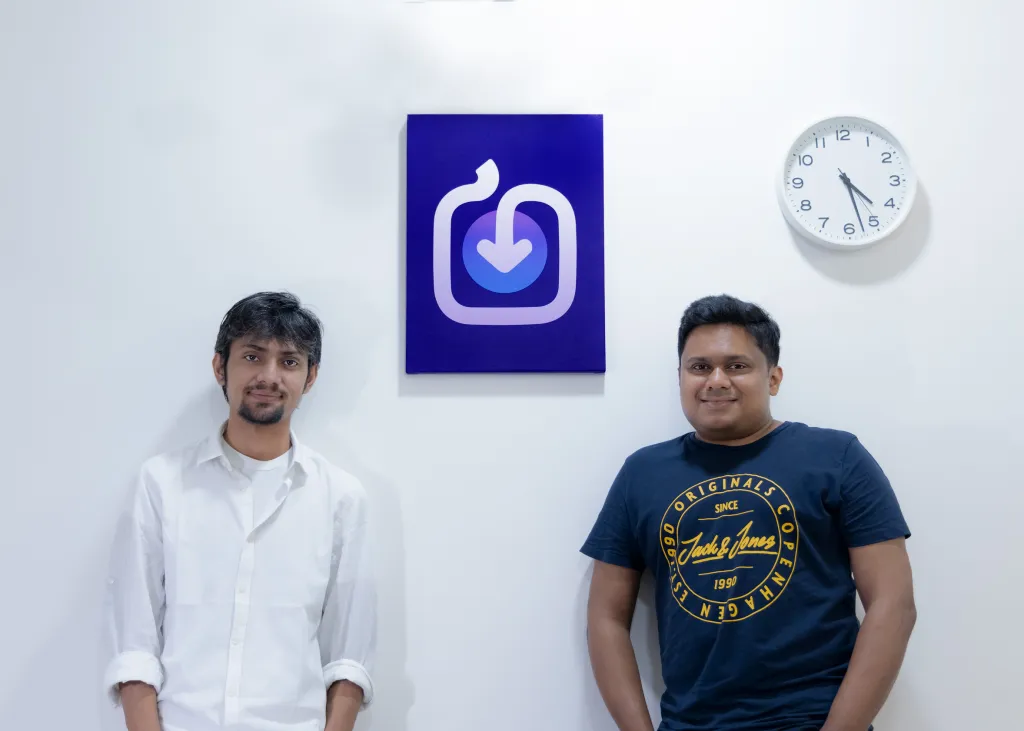
Now Jar is in the middle of a larger story, one that moves beyond habit-building into scale, profitability and a sharper, full-stack play in the gold value chain. The company is in talks to raise over $100 million, with WestBridge Capital issuing a term sheet, and Kotak Investment Banking advising on the round. The valuation being discussed sits around $500-$550 million, with multiple investors in the mix .
A funding round that doubles as a reset
For Jar, this isn’t just another capital raise, it’s a reset of narrative. Earlier, the company explored a $50 million fundraising led by Prosus that did not close after valuation differences, with investors offering $200-250 million while Jar sought $300-350 million.
The new talks place Jar in a different bracket, and they come alongside a financial turnaround that has become difficult to ignore.
The engine: turning “spare change” into ownership
The underlying product at Jar’s core leverages a very simple behavior: small savings, with low friction. Digital gold, stored in vaults, recorded in the digital world, and priced in micro-units, was the wedge that opened the door for this behavior. The premise is simple: if you can’t afford a small amount of physical gold, you can afford a small amount of digital gold.”
That idea has moved beyond startup marketing and into mainstream policy conversation. In the Rajya Sabha, Raghav Chadha highlighted the gap between what middle-class households can save at a time and what physical gold typically costs, pointing to digital gold’s ability to enable purchases worth a few rupees with vault storage and digital ownership records .
Scale: millions of users, wide reach
Jar claims 35 million+ registered users across 12,000+ pin codes. For any consumer fintech, that kind of reach matters because it changes what the company can become: a single-product app remains a feature; a distribution layer can evolve into a platform.
The second act: jewellery and insurance
Jar’s strategy is no longer limited to accumulation. The company has expanded into jewellery through its direct-to-consumer brand Nek, and it has also moved into insurance offerings.
This shift is telling. Digital gold brings users in; adjacent categories, especially those linked to gold purchase intent are where higher-value transactions and more durable revenue pools can emerge.
The numbers: revenue surge, losses narrowing, profitability signals
Jar’s FY25 filings point to a sharp financial inflection. Consolidated revenue rose to Rs 2,448 crore in FY25 from Rs 56.4 crore in FY24, while consolidated net loss narrowed to Rs 35.23 crore from Rs 104 crore.
On a standalone basis, Jar reported revenue of Rs 186.56 crore, EBITDA of Rs 15.07 crore, and net profit of Rs 13.17 crore. Another FY25 performance datapoint in the available material cites Rs 2,208 crore in operating revenue and indicates profitability momentum in the latter half of the year.
Read together, the story isn’t just growth, it’s an attempt to prove that a habit-led consumer product can graduate into a financially resilient company.
Where Jar is coming from?
Jar’s last major fundraising cycle was in 2022, when it raised capital with Tiger Global at valuations referenced around the $250 million to $300+ million range across accounts. That era rewarded speed and user acquisition. This one rewards proof, unit economics, repeat purchase behavior, and profitable growth.
If the $100+ million round closes at the discussed valuation band, it will be interpreted as a vote of confidence in Jar’s transition from a digital gold on-ramp to a broader consumer finance and commerce play linked to gold.
Jar’s challenge now is the same one that defines every breakout in the Ascendants category: turning distribution into defensibility. Micro-savings got India to download the app. The next chapter will be judged by whether Jar can own more of the customer’s intent, buying, gifting, protecting, and eventually building wealth, without losing the simplicity that made it scale in the first place.
Also Read: India Tech Startups Raise $10.5 Billion in 2025, Rank 3rd Globally