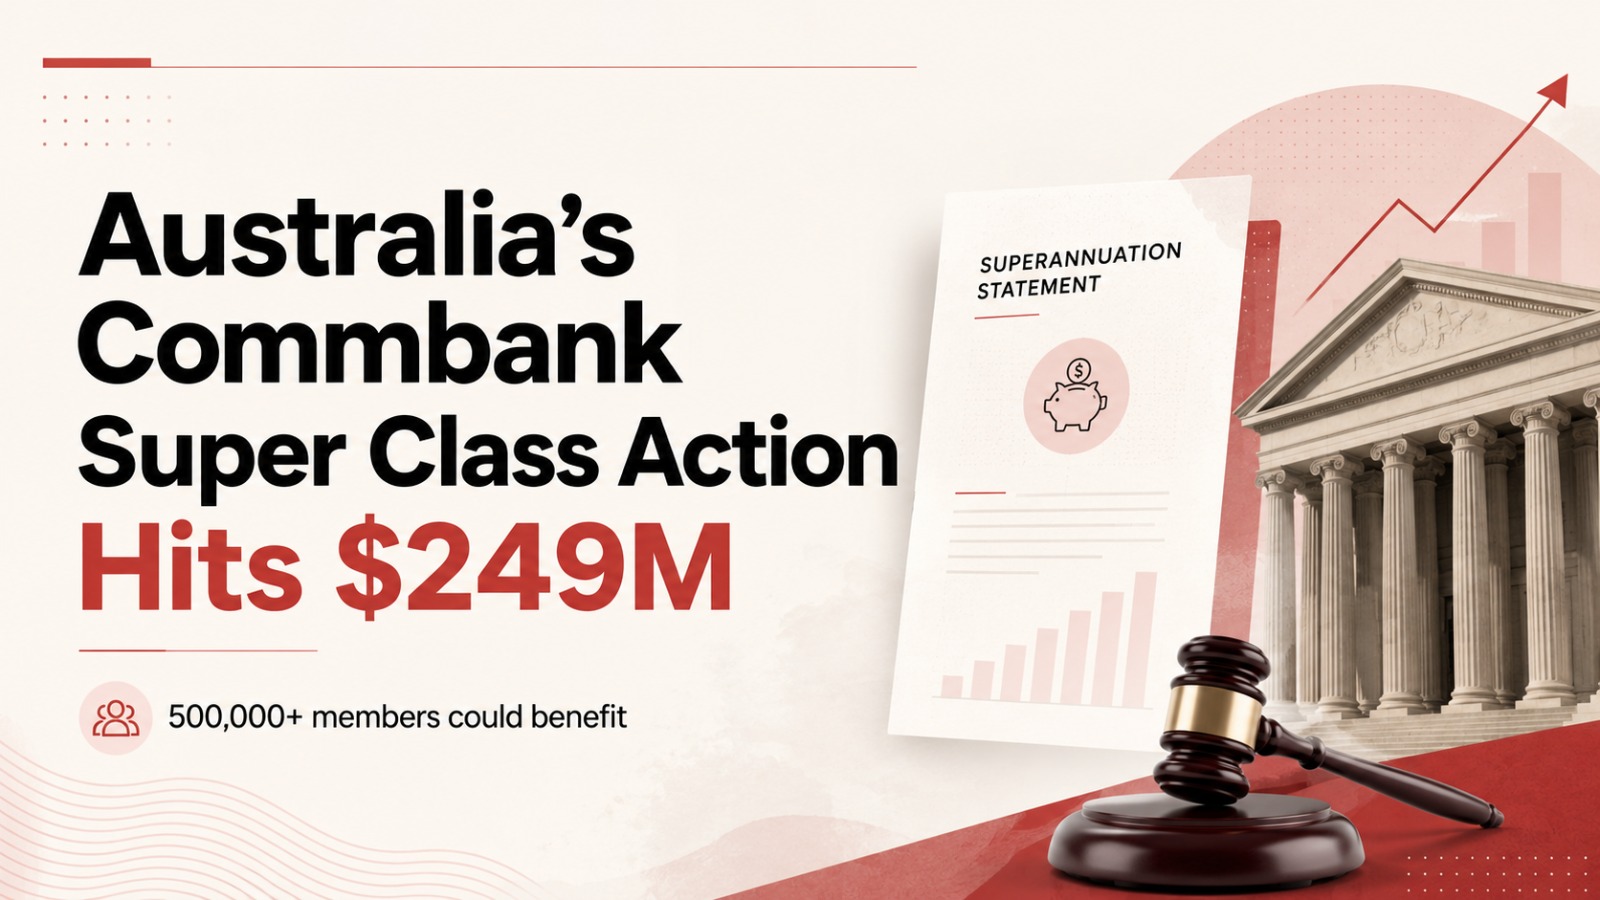
Commbank superannuation class action: More than half a million Australians could ultimately benefit from a $249 million settlement linked to the way retirement savings were invested in certain cash and deposit products connected with Commonwealth Bank.
The settlement brings a major class action closer to an end after proceedings were launched by Slater and Gordon Lawyers in 2018. The case was brought against Commonwealth Bank of Australia, Colonial First State Investments Limited, known as CFSIL, and Avanteos Investments Limited, or AIL.
There is an important qualification, however. The $249 million figure is an in-principle settlement, not a final court-awarded payout. It remains subject to approval by the Federal Court of Australia, and the respondents have not admitted liability or wrongdoing.
That distinction matters because the case concerned allegations about how members’ money was managed. The settlement resolves the litigation without the court having made a finding that those allegations were proven.
What was the Commbank Superannuation class action actually about?
The dispute centred on cash and deposit investments available through Colonial First State and Avanteos superannuation and wrap products.
The proceedings alleged that members received lower returns because their retirement savings were invested with CBA without sufficient efforts being made to obtain the best interest rates available.
The investments covered by the allegations were offered through CFS FirstChoice, FirstWrap and Commonwealth Essential Super, with the relevant period running from November 2008 until September 2021.
Slater and Gordon also alleged that CFSIL and AIL received undisclosed payments from CBA that created an incentive to place members’ savings with the bank at lower rates. The case further alleged that CBA benefited from gaining access to those savings at comparatively low interest rates.
Put simply, the case was not about a single bad investment or a sudden fall in the market. It was about whether superannuation trustees had properly protected members’ interests when deciding where cash and deposit savings should be invested and what return those savings should earn.
Why did interest rates matter so much?
The size of the settlement can appear surprising when the dispute revolves around differences in interest rates rather than the loss of an entire investment.
But superannuation operates over long periods.
Nathan Rapoport, Slater and Gordon’s class actions practice group leader, argued that even relatively small differences in annual returns can become substantial after years of compounding.
He said members could potentially lose tens of thousands of dollars by retirement if trustees failed to pursue better interest rates on cash and deposit investments. His broader point was that a few hundred dollars left invested inside super today can become a much larger amount over time.
That compounding effect is one of the clearest ways to understand the case.
A modest difference in interest earned during one year might not appear significant on a statement. But when the same issue affects savings repeatedly over several years, and the money would otherwise have remained invested until retirement, the eventual difference can become much larger.
How long did the alleged conduct continue?
The allegations covered a period of almost 13 years, from November 2008 to September 2021.
That unusually long timeframe is important because the length of time members’ money was allegedly affected helped increase the potential financial impact.
Rapoport said the settlement reflected both the seriousness of the allegations and the long period involved, as well as the amount of members’ savings invested by the trustees with CBA.
The class action itself began in 2018 following the Banking Royal Commission, which brought greater scrutiny to conduct across Australia’s banking, superannuation and financial services sectors.
Who could receive money?
More than half a million Australians are estimated to potentially qualify for a share of the settlement.
That does not mean each eligible member will receive an equal portion of $249 million.
If the Federal Court approves the settlement, the money will be distributed under a court-approved scheme. That scheme is expected to determine who qualifies, how individual amounts are calculated and how payments are ultimately distributed.
The final amount received by an individual member therefore cannot be reliably calculated simply by dividing $249 million by the estimated number of people affected.
Nine reported that members are not expected to have to take action to obtain their share and that payments are most likely to flow into superannuation accounts after court approval.
The precise distribution process, however, will depend on the scheme approved by the court.
Who were the lead applicants?
Two individual experiences help illustrate how the investments involved in the case worked.
Lead applicant Wendy Gibson joined Colonial’s FirstChoice Wholesale Personal Super in 2005 and invested in term deposits offered through the product between 2011 and 2019.
Gibson said she was surprised when she learned about the alleged conduct and expressed relief that the long-running proceedings were nearing a conclusion.
Another lead applicant, Peter Currie, joined Avanteos’ FirstWrap Plus Personal Super in 2012 and held money in a cash account through the product.
Their experiences underline why the case extended beyond conventional ideas of risky investments. The dispute involved products such as cash accounts and term deposits, where members would ordinarily be focused on preserving savings and earning interest rather than taking significant investment risk.
Did CBA and the fund managers admit wrongdoing?
No.
The settlement was reached without an admission of liability.
CBA said in its statement confirming the in-principle agreement that CBA, CFSIL and AIL continued to deny the allegations and made no admission of liability or wrongdoing.
That is a crucial part of the outcome.
A settlement ends litigation on agreed terms. It does not, by itself, establish that every allegation made in the proceeding was proven.
What happens next?
The immediate next step is Federal Court consideration of the settlement.
Until approval is granted, the $249 million should not be treated as money already paid to individual superannuation members.
If the court approves the arrangement, the distribution scheme will become the key document for affected members. It will set out eligibility rules, how individual entitlements are calculated and how distributions will be made.
Slater and Gordon has described the $249 million agreement as the largest settlement it has secured in a group proceeding.
For members, though, the significance of the case is less about the headline number than the principle underneath it: in superannuation, apparently small differences in the return earned on savings can become much more meaningful when those differences persist and compound over years.
That is ultimately why a dispute over cash and deposit interest rates stretching from 2008 to 2021 has ended with a settlement measured in hundreds of millions of dollars.
Also Read: Nexeon Raises €116.7 Million With UK Pilot Facility at the Heart of Its Silicon-Anode Scale-Up