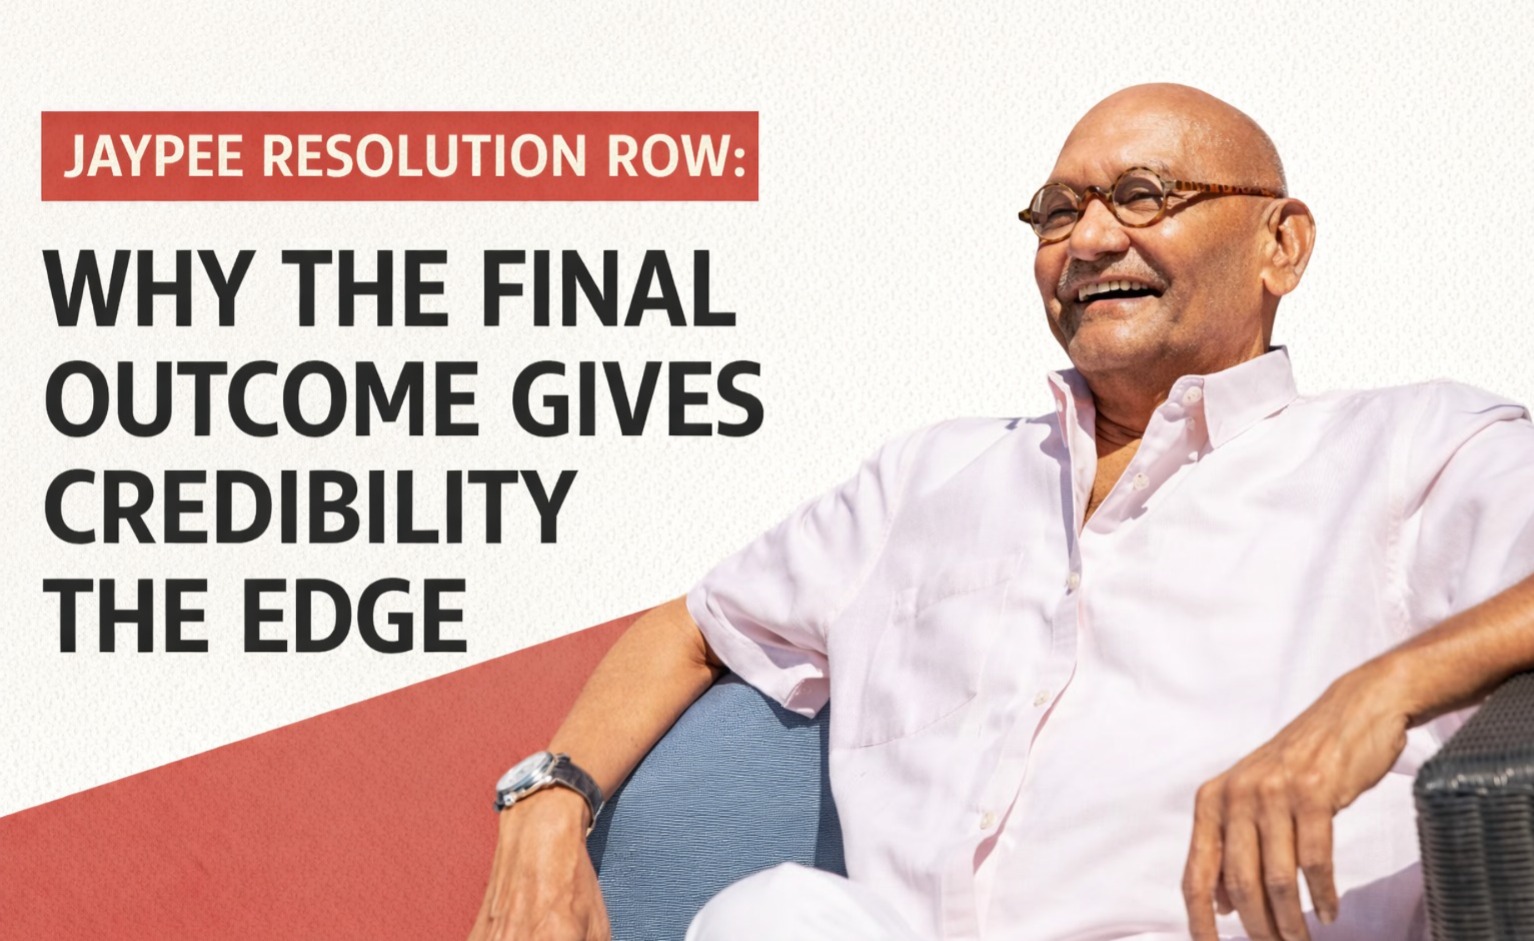
Anil Agarwal’s recent public note on the Jaypee asset brought philosophy, memory and personal conviction into what is otherwise a hard-edged insolvency contest. Framed through the Bhagavad Gita and his past interactions with Jaypee Group founder Jaiprakash Gaur, the Vedanta chairman’s message was emotional, restrained and clearly designed to present the issue as one of trust and fairness.
It also ensured that the spotlight shifted back to a central question: if Vedanta had emerged as the highest bidder at one stage of the process, how did the asset move elsewhere?
The answer, going by the contours of the insolvency framework and the facts cited around the bidding, appears to lie in a distinction that is often lost in public debate. In such cases, being numerically ahead on one parameter is not the same as having a binding claim on the asset.
That distinction is where this story really sits.
At the heart of the public narrative is Vedanta’s position that it was the highest bidder. But in stressed-asset transactions, that phrase can sometimes conceal more than it reveals.
What lenders typically examine is not just the headline number, but the overall quality of the resolution plan. Net present value, or NPV, may be one way of ranking bids, but it is not the only lens through which creditors assess recoveries. The structure of payments, conditions attached to the offer, execution certainty, legal sustainability and implementation timelines all matter.
That means a bidder can be ahead on limited NPV and still fall short when the full plan is assessed. Creditors are not expected to choose in a mechanical fashion. Their role is to evaluate which plan is more bankable, more executable and ultimately more dependable.
In that context, the final outcome appears less surprising than the public commentary suggests.
Creditors were always expected to look beyond H1 status
One reason the fairness argument has found traction in public discourse is that “highest bidder” sounds conclusive. In financial reality, it often is not.
In many such processes, H1 status is only one stage in a larger commercial assessment.
It may indicate who is leading on a narrow metric, but it does not automatically create an enforceable right to acquire the company. If the bid documents themselves made clear that topping the table on a limited NPV basis would not guarantee control of the asset, then the lenders’ later decision to weigh other factors was not a deviation from process. It was the process.
That point matters because it shifts the debate away from emotion and back toward institutional design. Insolvency resolution is meant to maximize value through creditor judgment, not through a single-number auction logic.
Implementation risk matters as much as valuation
A second issue is the structure of the bid itself.
The concern, as indicated, was not just valuation but the presence of conditions in Vedanta’s plan that made implementation more difficult. For lenders, that is not a secondary issue. A resolution plan is only as strong as its ability to be delivered. If a proposal looks attractive on paper but carries enough caveats to create uncertainty, creditors are within their rights to discount that offer in practical terms.
This is where financially sophisticated buyers often separate themselves. In a competitive insolvency process, a cleaner and more executable bid can be more compelling than a richer but more conditional one.
From that perspective, the eventual preference for another bidder can be read not as arbitrariness, but as a rational decision rooted in execution discipline.
The funding timeline also raises questions
Another factor that weakens Vedanta’s claim of unfair treatment is preparedness.
It is significant that when reports first surfaced around Vedanta being highest on NPV, the company itself indicated to lenders and creditors that the matter was not final and that evaluation would take place across multiple parameters. That suggests there was already an understanding inside the process that no finality had been reached.
Equally important is the issue of financing readiness. If funds were not raised until as late as November, lenders would understandably see that as a sign of delayed preparedness. In insolvency, timing is not cosmetic. A bidder is judged not only by intent, but by how ready it is to close, implement and carry the asset forward.
Financial seriousness in these situations is demonstrated through certainty, not just enthusiasm.
In stressed assets, track record always follows the bidder
There is also the broader question of credibility.
Creditors tend to look closely at a bidder’s past conduct, especially in sectors where capital intensity, regulatory complexity and execution risk are high. If there is a history of stepping back from awarded projects, citing market conditions after commitments, or delays in executing previously acquired assets, that history inevitably enters the room even if it is not the headline issue.
That is not prejudice. It is commercial memory.
For lenders deciding between competing plans, track record is part of risk assessment. A bidder’s past ability, or inability, to follow through becomes relevant because the objective is not merely to approve a plan but to back a resolution that will actually hold.
No final vesting, no automatic grievance
The strongest emotional line in Agarwal’s note is that something promised should not be withdrawn. It is an effective line. But it depends on one crucial assumption, that a binding promise had in fact been made.
From the facts cited, that does not appear to be the case.
If lenders never took a formal decision declaring Vedanta the final winner, then the claim that something was later “taken away” becomes harder to sustain. Being informed that one is leading at an interim stage is not the same as receiving conclusive approval from the Committee of Creditors. There is a substantial difference between procedural communication and final commercial award.
That difference is precisely why public messaging and legal position are not always aligned.
Why the final outcome appears commercially defensible?
Viewed through a finance lens, the final acquisition appears easier to defend than the post-bid rhetoric suggests.
Creditors were entitled to look at the totality of the plan, not just the NPV ranking. They were entitled to assess conditions attached to bids. They were entitled to examine implementation certainty, funding readiness and bidder track record. And if the process rules themselves did not guarantee the asset to the bidder ranked first on a limited metric, then the decision to move toward a more credible execution outcome falls well within commercial logic.
That does not make the losing side’s disappointment any less real. But disappointment is not the same as procedural unfairness.
A public moral case, a private financial reality?
What Agarwal did effectively was turn a technical process into a human story. He wrote about trust, legacy, grace and restraint. It was thoughtful messaging, and it gave Vedanta the moral vocabulary of the dispute.
But insolvency frameworks are not designed to reward moral vocabulary. They are designed to test bids for value, certainty and implementability. That can often produce outcomes that sound less poetic, but are more durable.
And that may be the real lesson here. In a modern resolution process, the winning bid is not always the one that sounds best in public. It is usually the one that gives creditors the highest confidence that the transaction can survive contact with reality.
The broader takeaway
The Jaypee episode underlines a familiar truth in Indian distressed-asset deals: leading on paper is not the same as winning in substance.
A bid may top a narrow financial measure and still lose out if lenders believe another plan is stronger overall. That does not necessarily reflect favouritism or inconsistency. It may simply reflect the difference between valuation optics and resolution credibility.
In that sense, the final outcome looks less like a reversal and more like a choice made on broader commercial grounds. And in insolvency, that is often what fairness actually looks like.
Also Read: Pronto: Instant Home Cleaning Services in Just 10 Minutes!