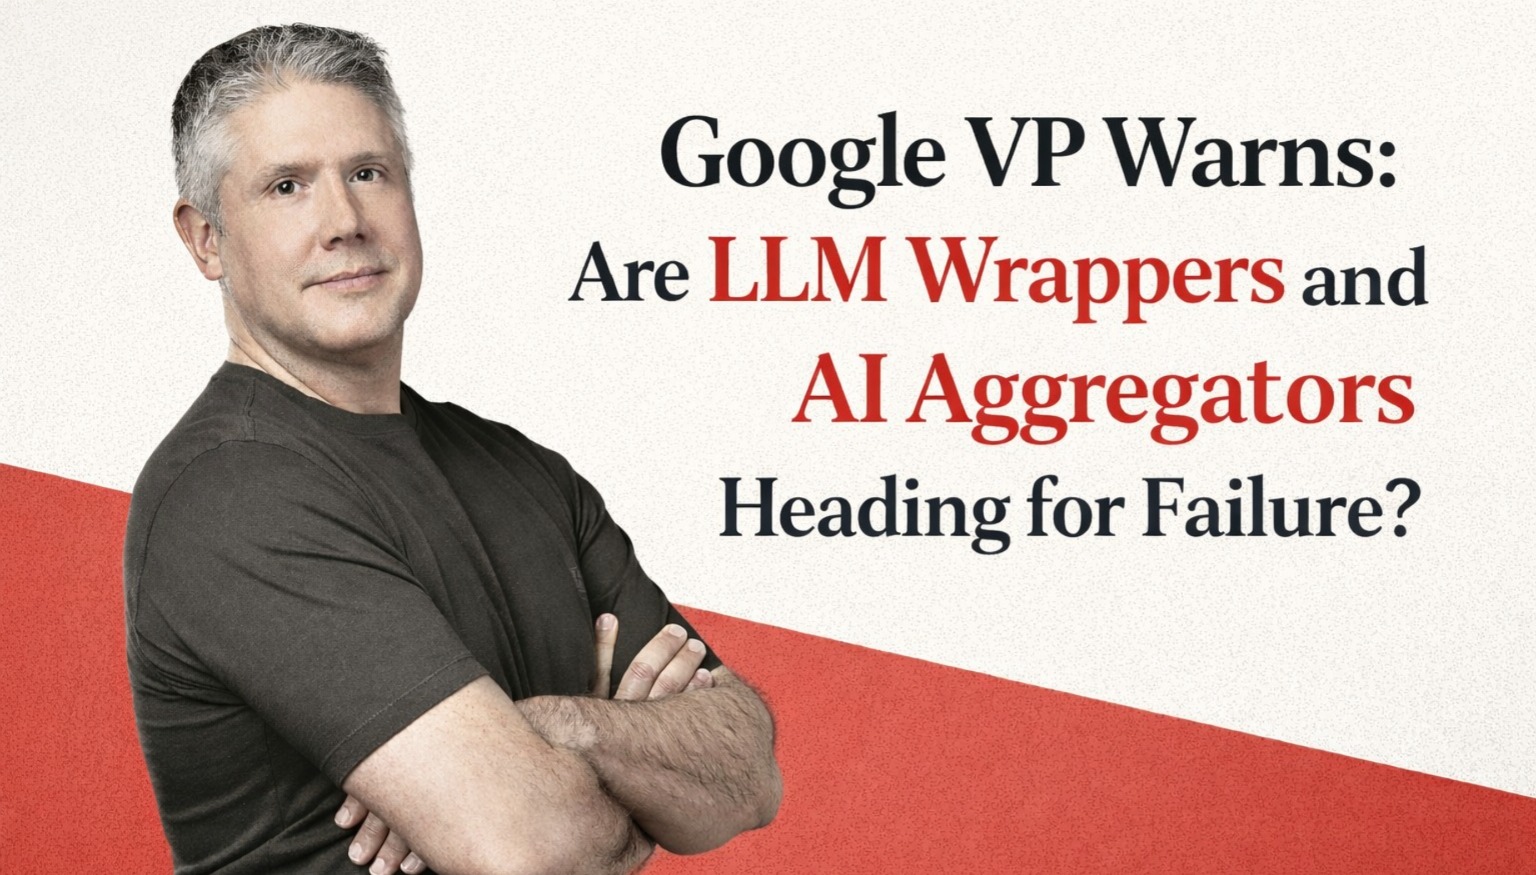
The generative AI boom has been so loud and so fast, that it’s easy to forget how quickly markets learn to ignore copy-paste businesses. Now Google’s Darren Mowry is arguing that two once-fashionable startup plays are starting to look less like rocket ships and more like cautionary tales: LLM “wrappers” that don’t truly differentiate, and “AI aggregators” built mainly as middle layers.
Mowry, who leads Google’s global startup organization across Cloud, DeepMind and Alphabet, says startups leaning on these hooks should treat it like a dashboard warning: their “check engine light” is on.
The problem with “just a UI on top”
Mowry’s critique isn’t that every wrapper is doomed. It’s that the era of thin value-add is ending.
LLM wrappers, as he describes them, are companies that wrap existing models, Claude, GPT, or Gemini, with a product or UX layer to solve a problem. The risk comes when the startup’s “magic” is basically the base model doing all the heavy lifting.
“If you’re really just counting on the back-end model to do all the work and you’re almost white-labeling that model, the industry doesn’t have a lot of patience for that anymore,” Mowry said on TechCrunch’s Equity podcast. He warned that wrapping “very thin intellectual property around Gemini or GPT-5” is a signal you’re not meaningfully differentiating.
His prescription is straightforward: defensibility. “You’ve got to have deep, wide moats…either horizontally differentiated or something really specific to a vertical market” to “progress and grow,” he said. He pointed to Cursor (a GPT-powered coding assistant) and Harvey AI (a legal AI assistant) as examples of wrapper-style companies that do have deeper moats.
Mowry suggested startups can’t assume they’ll win attention merely by “slap[ping] a UI on top of a GPT” the way they might have when distribution was easier, he referenced the mid-2024 moment around OpenAI’s ChatGPT store and said the real challenge now is building sustainable product value.
“Stay out of the aggregator business”: Google VP
If wrappers are a warning sign, Mowry’s view on aggregators is even sharper.
He describes AI aggregators as a subset of wrappers that bundle multiple LLMs into one interface or API layer, routing queries across models and offering an orchestration layer that can include monitoring, governance, or evaluation tooling.
He cited Perplexity and OpenRouter as examples of this kind of “one layer to access many models” approach. But for new startups trying to enter, his advice is blunt: “Stay out of the aggregator business.”
Why? Because, as he frames it, users increasingly want “some intellectual property built in” not just routing based on compute or access constraints, so they’re sent to the right model at the right time for their needs. In other words: orchestration alone is getting commoditized.
A cloud-era déjà vu
Mowry anchored his warning in an older tech cycle. He said today’s AI aggregator squeeze resembles the early days of cloud computing in the late 2000s/early 2010s, when startups tried to resell AWS infrastructure by bundling tooling, billing consolidation, and support.
Once Amazon built more enterprise tools and customers learned to manage cloud services directly, most resellers were pushed out. The survivors, he said, were the ones that added “real services” like security, migration, or DevOps consulting.
He sees a similar dynamic emerging now: AI aggregators face margin pressure as model providers expand into enterprise features themselves, which could sideline middle layers.
Where he’s more optimistic?
Mowry isn’t painting a doom-and-gloom picture of AI startups broadly. He said he’s bullish on “vibe coding” and developer platforms, calling out a strong year in 2025 with startups such as Replit, Lovable, and Cursor drawing major investment and customer traction
He also expects growth in direct-to-consumer tech that puts powerful AI tools in customers’ hands, pointing to a use case: film and TV students using Google’s AI video generator Veo to bring stories to life.
And beyond AI, he flagged momentum in biotech and climate tech, citing venture investment interest and the “incredible amounts of data” startups can use to create new kinds of value.
What founders can take from this?
Mowry’s message, stripped of buzzwords, is essentially a sorting mechanism:
- If your startup’s value is mostly a front-end on someone else’s model, investors and customers may start treating it as replaceable.
- If your business is primarily a middle layer between users and model providers, you may be competing with the platforms themselves as they move up the stack.
- The businesses most likely to keep compounding are the ones with real moats, deep product differentiation or strong vertical specificity and value that doesn’t vanish the moment the underlying model gets upgraded.
That’s a tougher standard than “ship fast and wrap an API.” But in a market where the baseline keeps rising, it may be the only standard that lasts.
Also Read: PaleBlueDot AI Enters Unicorn Club as Neocloud Infrastructure Attracts Major Capital