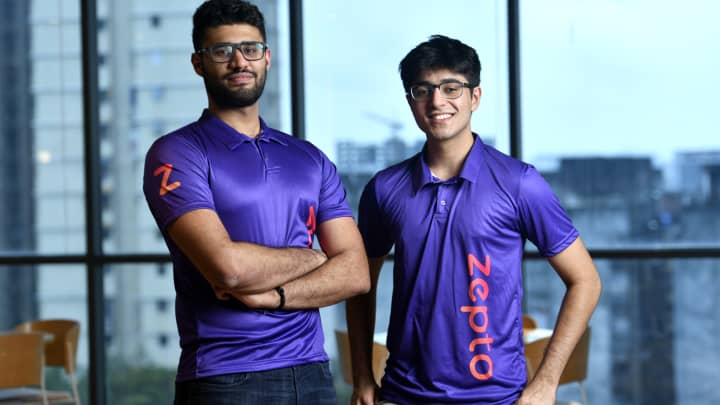
Zepto’s confidential filing for a proposed ₹11,000 crore initial public offering is not merely another startup milestone. It marks a moment of reckoning for a sector that has grown at breakneck speed, drawn enormous capital, and reshaped urban consumption habits in record time.
If the company proceeds with a listing in the July-September 2026 window, the four-year-old firm will become one of the youngest venture-backed startups in India to test itself in the public markets.
That alone makes the development significant. But the real story is deeper. Zepto’s IPO move is forcing a larger question into the open: can India’s quick commerce business, built on speed, convenience and relentless expansion, convince public investors that it can become a durable and financially credible model?
For now, the company offers both a compelling growth story and a difficult balance sheet.
In FY25, Zepto reported revenue of ₹9,669 crore, up 129% year-on-year.
It had generated gross sales of around ₹26,000 crore. The company had grown beyond 900 dark stores by September 2025 and served over 70 cities, processing millions of orders each day. Purely from an operational point of view, it’s hard to find many consumer internet businesses growing this fast.
The numbers speak for themselves. Zepto isn’t any more seen as a startup in fast growth experimenting with a specialized model. They’ve become one of the main players in the Indian market of quick commerce, capturing about 30% market share, after Blinkit’s 50%. In an industry where consumer loyalty hinges upon factors like speedy delivery, a wide product portfolio, and habitual behavior, market shares like this aren’t achieved without reason.
But the numbers also reveal the cost of that ambition.
Zepto posted a net loss of ₹3,367 crore in FY25, a 177% increase. Its monthly cash burn stood in the ₹1,000-1,100 crore range. The company has already raised $1.8 billion and is currently valued at $7 billion. Those figures underline the core tension at the heart of quick commerce: growth can be explosive, but it is expensive, and the bill eventually becomes impossible to ignore.
That is why the most important part of Zepto’s IPO journey may not be the filing itself, but the shift in the story it is now choosing to tell.
In private markets, the language of startup ambition is often unapologetically aggressive.
Investors back founders who promise rapid land grabs, category dominance and hypergrowth, even at significant cost. Public markets are less patient. They do not just reward growth; they interrogate its quality. They want visibility on margins, discipline in capital allocation, and a believable path to profitability.
Zepto appears to understand that change in audience.
Its repositioning around “disciplined 40-50 city operations” signals more than a communications tweak. It reflects a broader attempt to present itself not simply as a company that can grow fast, but as one that knows where growth should slow, consolidate and eventually begin to pay for itself. That distinction matters. Public investors are not only buying into the next phase of expansion; they are also buying into management judgement.
This is where Zepto’s timing becomes especially interesting.
Unlike an earlier generation of tech IPO candidates, it is coming to market in a space where direct public comparisons already exist. Zomato has been listed since 2021, and Swiggy followed in November 2024.
That changes the conversation. On one hand, comparables make it easier for investors to understand the sector. On the other, they remove some of the mystery that high-growth startups often benefit from in private rounds. Zepto will not be valued in isolation. It will be measured against listed rivals, against operating discipline, against market share efficiency, and against how convincingly it can answer the profitability question.
That will shape everything from investor roadshows to valuation expectations.
The quick commerce model has undeniably worked in India in a way that few global markets have managed to replicate. Consumers have embraced it, daily ordering behaviour has deepened, and the category has expanded well beyond emergency top-ups into mainstream convenience shopping. But public markets do not reward relevance alone.
They demand resilience. A model can be culturally sticky and operationally impressive, yet still struggle to satisfy investors if margins remain elusive.
That is what makes Zepto’s IPO more than a company-specific event. It is fast becoming a test case for the sector itself.
For founders across India’s startup ecosystem, the move offers at least three clear lessons.
The first is that narrative management evolves with capital sources. The story that wins venture money is not always the story that earns public trust. Founders who want to go public cannot keep speaking in the language of endless conquest. They need to show maturity, restraint and a tighter grip on fundamentals. Zepto’s shift from a hypergrowth pitch to a more disciplined operating message suggests it knows that public markets expect a different kind of confidence.
The second is that speed to IPO is not just a badge of ambition; it is a stress test of execution. Reaching the public market within four years of founding is rare. It requires rapid revenue expansion, a credible market position, and enough organisational maturity to withstand scrutiny that is far more demanding than private boardrooms. Public listing is not simply a financing event. It is a transition into constant examination.
The third is that market timing can outweigh perfect financial readiness. Zepto is not profitable. That much is clear. Yet with 129% revenue growth and a 30% market share, it appears willing to test the market while investor appetite is still open to category leaders with scale. In startup finance, readiness is often imperfect. The real question is whether the market believes the company has earned the right to make its case now.
That question will define the months ahead.
The listing of Zepto has brought new life to the startup-to-IPO pipeline in India, but it has also brought new attention to a business model that is still riddled with questions. It is no longer enough for investors to see growth numbers. They will seek answers to what lies behind that growth.
Is there any advantage in scalability? Can we expect more success by concentrating on operations in fewer cities? Will the burn rate begin to show a declining trend without compromising the underlying value proposition?
The answers will matter far beyond a single IPO.
If Zepto can persuade public investors that quick commerce has a viable long-term operating logic, it will strengthen confidence in the wider sector. If it struggles, doubts around the economics of ultra-fast delivery could intensify. Either way, the listing is shaping up as a litmus test for one of India’s most closely watched internet categories.
Also Read: Atlas Secures $6 Million Seed Funding to Expand AI Solutions for Accounting Firms