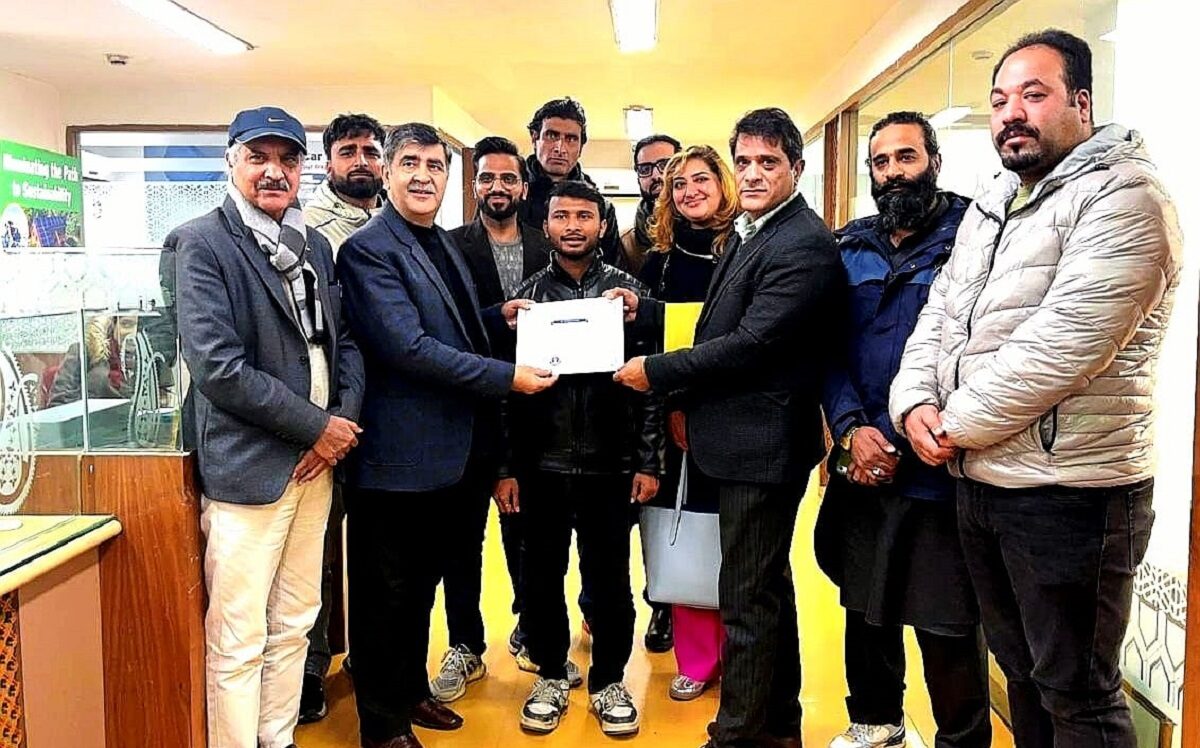
Kashmir Startups Booming: On a cold Saturday morning at Jehangir Chowk, the usual rush outside the J&K Bank branch had a different kind of energy. Instead of customers with passbooks and cheques, the lobby filled with founders carrying pitch decks, product mock-ups and early-stage business plans, all hoping to answer the same question: how do we actually finance our ideas?
The interaction, organised by Startup Kashmir in collaboration with J&K Bank, was designed as a practical clinic on business loans, funding schemes and documentation, not a motivational talk. Over a few hours, bank officials, startup mentors and founders went line by line through what it takes for a young Kashmiri venture to become “bankable”.
Kashmir Startups: From Ideas to Balance Sheets
Opening the session, Startup Kashmir CEO Shahid Ansari underlined a reality many early-stage founders hesitate to confront: a strong idea is not enough if it is not backed by a clear financial roadmap. He urged entrepreneurs to think beyond prototypes and branding and start engaging with projections, repayment plans and risk assessment, the language banks understand.
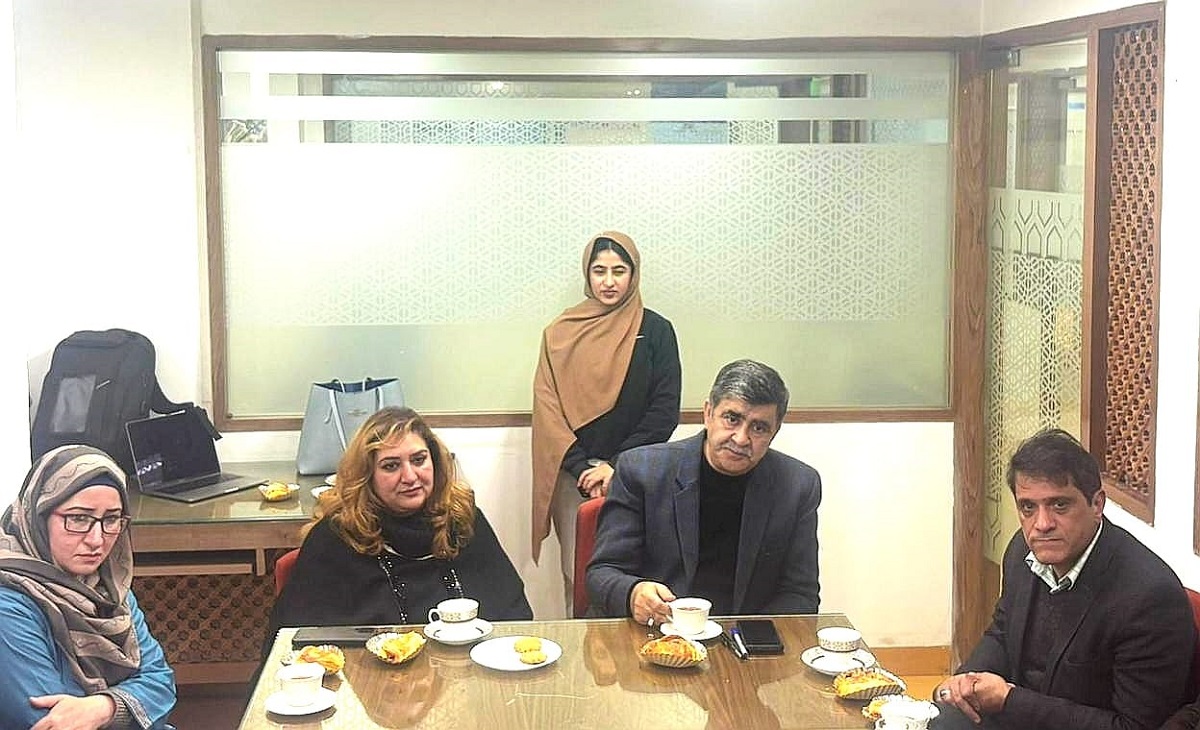
Startup Kashmir director Khair Ull Nisa Shah widened the lens, pointing to the importance of mentorship and ecosystem support. In her view, fundraising and bank credit are not standalone activities; they work best when young companies are embedded in a network of advisors, peers and institutions that can guide them through each step of compliance and growth.
Rather than speeches from a stage, the session was structured as a working conversation. Founders were encouraged to ask specific, sometimes basic, questions about banking processes many usually hesitate to raise across the counter.
Real Startups, Real Questions
The list of participating ventures reflected the diversity of Kashmir’s emerging startup scene. Among the founders present were:
- Furqan Qureshi, building Cartzu
- Rizwan Bashir, representing Helixionlink
- Sarwan Kumar of Safar Sarthi
- Bilal Ahmad, who runs Bilal’s Innovative Solar Automobiles
- Amir Mir of Upheld AI
- Wajahat Dar of Harmain Services
Though their sectors range from mobility and services to technology and clean energy, their doubts looked remarkably similar:
- What does a bank look for before clearing a business loan?
- How should a startup structure its documentation?
- Which government schemes are actually accessible to an early-stage company in Kashmir?
The discussion moved case by case, with founders walking bank officials through their models and getting feedback on where they stood in terms of readiness, both financially and on paperwork.
What the Bank Put on the Table
For J&K Bank, the event was an opportunity to signal that it wants to be more than a distant lender for the region’s startups.
Branch head Syed Ishrat Hussain explained the range of financial instruments available to small and growing enterprises, from standard business loans and credit facilities to government-backed initiatives designed for startups.
He broke down eligibility criteria, typical documentation gaps, and the step-by-step process a founder can expect once an application is filed.
Crucially, Hussain did not restrict the bank’s role to sanctioning or rejecting files. He extended an open invitation to startups to treat the Jehangir Chowk branch as a resource centre, a place they could approach early in their journey to understand requirements, refine proposals and avoid avoidable mistakes before applying.
That gesture, simple on the surface, hinted at a shift in posture: from gatekeeper to partner.
Demystifying the ‘Fear of the Bank’
For many young founders in Kashmir, the idea of dealing with banks still carries a mix of hesitation and confusion. Terms like collateral, credit history and scheme eligibility are often seen as barriers rather than tools.
Participants at the session said the conversation helped strip away some of that anxiety. One entrepreneur summed it up by noting that while many in the room had been nurturing ideas for years, they lacked a clear picture of how formal finance could support those ideas.
The interaction, they felt, turned a vague hope of “getting a loan someday” into a more concrete checklist of steps they could start on immediately.
Instead of general advice, founders walked away with individual guidance: which documents to prepare next, which loan products might fit their stage, and which schemes were worth exploring based on their sector.
A Small Room, A Larger Signal for Kashmir’s Startup Ecosystem
While the meeting at Jehangir Chowk involved a limited group of entrepreneurs, it pointed to a larger trend. Over the past few years, Kashmir has seen a quiet rise in small, locally rooted startups, in sectors like logistics, services, technology, tourism and renewable energy.
Many of these ventures operate with modest resources and personal savings, rarely approaching formal financial institutions until they hit a crisis point.
By bringing founders and a local bank into the same room, away from formal counters and long queues, the session attempted to change that pattern. Startup Kashmir’s role as an intermediary, pairing mentoring support with access to bank officials, is aimed at ensuring that entrepreneurs engage with finance as a planned part of their growth journey rather than a last-minute scramble.
For J&K Bank, actively inviting startups to use its space and expertise is also a way of future-proofing its own portfolio, positioning itself early in the lifecycle of ventures that may grow into significant local employers and borrowers.
Beyond One Session
The Jehangir Chowk interaction did not promise instant funding or overnight success. What it offered was something more basic but often missing: clarity.
Founders left with a better understanding of what banks expect, whom to approach, and how to prepare themselves for formal finance. The organisers, in turn, gained a sharper sense of the everyday hurdles that keep many Kashmiri startups from even reaching the loan application stage.
If such conversations continue and expand to more sectors and districts, Kashmir’s startup story may increasingly be written not just in pitch events and social media posts, but also in properly structured loan files, cleared credit limits and long-term partnerships between local entrepreneurs and local banks.
For now, that process has taken one more step forward inside a Srinagar bank branch where, for a few hours, balance sheets and business dreams finally sat at the same table.
Also Read: Elon Musk Explains His Obsession With the Letter ‘X’ in New Nikhil Kamath Teaser