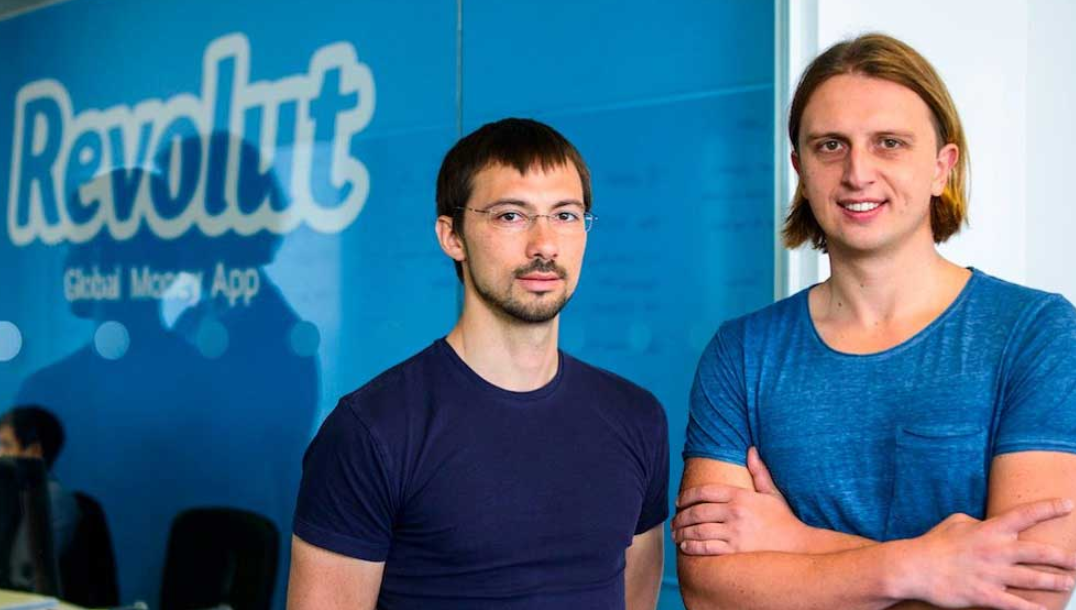
Revolut has lined up a $3 billion fundraise that values the London-based fintech at about $75 billion, consolidating its position as Europe’s most valuable startup and signaling continued investor conviction in full-stack digital finance.
What’s new?
People familiar with the deal say the round was oversubscribed and stitched together without bankers, an uncommon choice at this scale. The transaction blends fresh primary capital with a secondary sale, giving early investors and employees a path to liquidity. It follows a tender offer in August in which Revolut repurchased shares at a $45 billion valuation; a portion of those shares is now being resold to new backers at the higher mark.
The growth math behind the valuation
Founded in 2015 by CEO Nik Storonsky and CTO Vlad Yatsenko, Revolut has evolved into a “financial superapp,” spanning current and savings accounts, stock and crypto trading, bill payments, budgeting tools, and cross-border transfers. The company serves roughly 65 million customers and, by its cadence, is adding about a million users every 17 days, momentum that helps explain the near two-thirds increase in valuation over the past year.
How the money will be used
Revolut plans to channel the new capital into an aggressive expansion push:
- Entry into 30 additional markets
- Around $13 billion of investment aimed at reaching 100 million users
- A continued focus on obtaining full banking licenses market by market, or acquiring banks outright where that is the faster route to a regulated footprint
- These moves keep the strategy squarely on distribution and regulation: be present where the users are, and hold the permissions needed to offer the widest possible product set.
The Significance
At a $75 billion price tag, Revolut sits in rare air globally for private fintechs. The latest mark strengthens its case as a category leader in Europe and underscores investor preference for platforms with diversified revenues and deep user engagement rather than single-product fintechs. Industry chatter has suggested long-term targets that could push valuation toward $150 billion if execution holds, placing Revolut in the neighborhood of Europe’s largest incumbent banks by market value.
The fine print
- Deal structure: A mix of primary and secondary gives the company growth capital while letting early holders realize gains, often a stabilizing factor for later-stage cap tables.
- Capital efficiency: Running an oversubscribed process without bankers suggests tight control over fundraising and narrative, useful as Revolut scales across regulated markets.
- Regulatory path: The insistence on full licenses or bank acquisitions, signals Revolut’s preference to own the regulatory stack rather than rely solely on partnerships, reducing dependency risk as it broadens into credit, savings, and investment products.
Revolut’s trajectory highlights a structural shift: the ascent of universal, app-first finance platforms that blend payments, deposit-like products, and retail investing under one roof. Scale and the data flywheel it enables, has become the defensible moat. With user growth running at a million every 17 days and fresh firepower on hand, the company is positioned to press that advantage into new geographies while deepening services where it already leads.
Execution will hinge on three fronts already flagged by the company’s plan: winning licenses (or banks) in priority markets, converting sheer user scale into higher-margin products, and sustaining trust in an environment where regulatory expectations only rise with size. If those pieces fall into place, the distance between Revolut and Europe’s legacy banking giants once unthinkable, could continue to shrink.
Also Read: Inside Floweraura’s Bloom into a ₹100 Cr Gifting Giant